SELF-EMPLOYED BUSINESS OWNERS JUGGLING MULTIPLE DEBTS
Take a deep breath. Your debts could be one repayment, not five.
Tax debt, credit cards, car and business loans can add up fast when you're self-employed. Debt consolidation may help you simplify your repayments and ease the pressure on your cash flow.
CLICK BELOW TO WATCH FIRST!
Start here: 4 quick questions to see what options could suit you
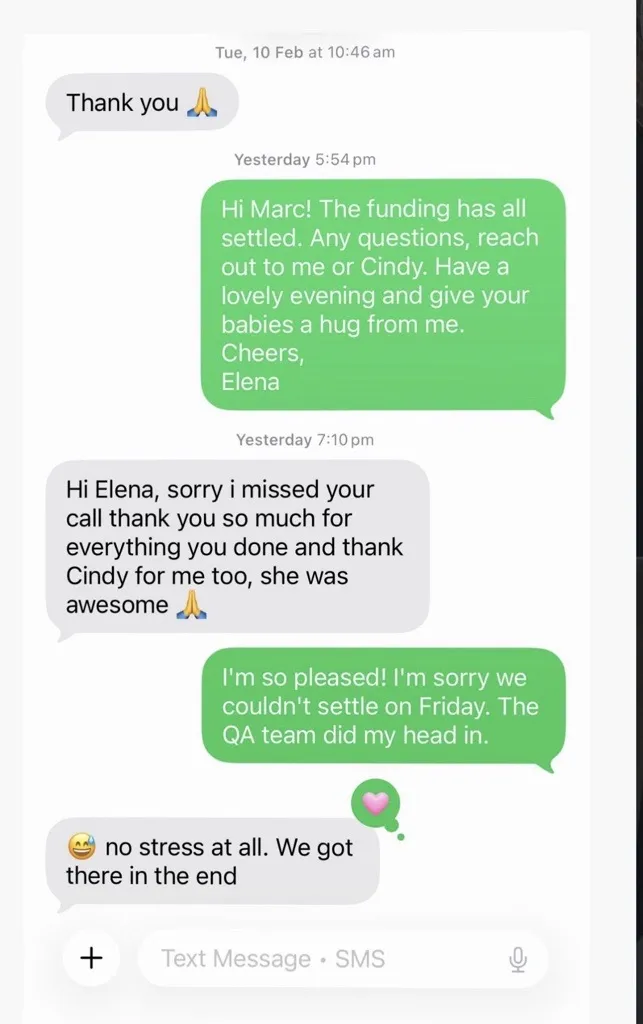
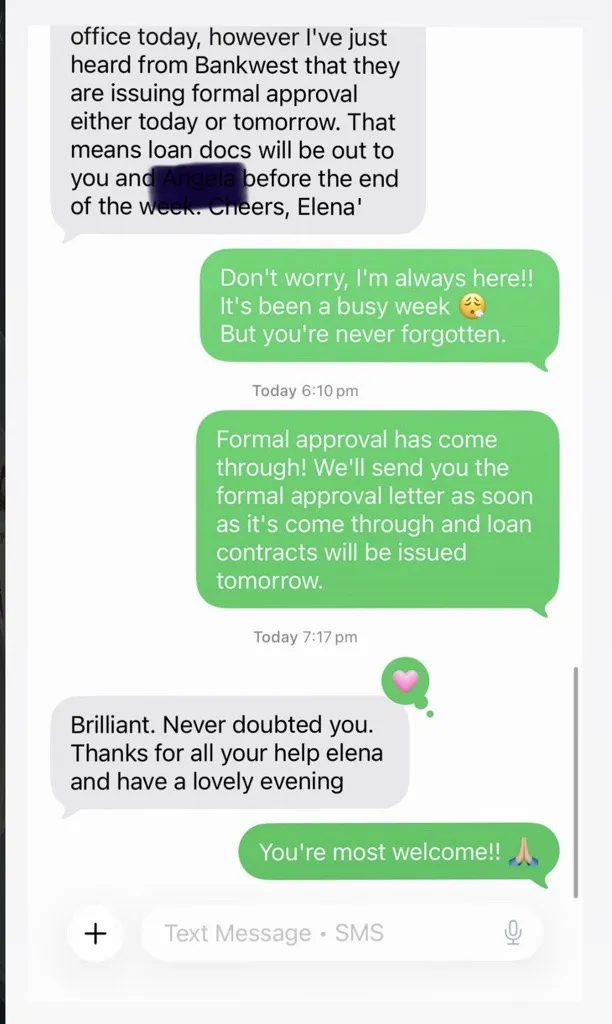
TESTIMONIALS
What others are saying
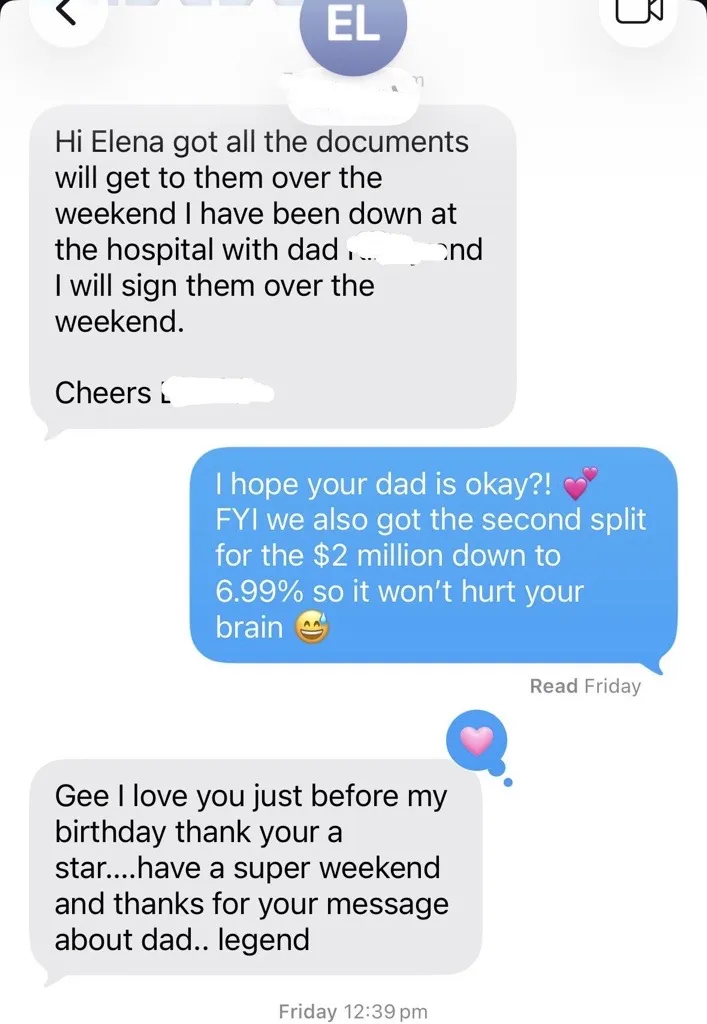
For Australians juggling multiple debts who need one simple repayment
ATO debt or payment plans
multiple credit cards
car and equipment loans
business loans and overdrafts
income through a trust or company
tight cashflow from high repayment
STILL NOT SURE?
Frequently Asked Questions
Here's what we usually get asked
What is debt consolidation?
It's when you combine several debts, like ATO debt, credit cards, car loans or business loans, into one loan with one repayment. For many people this is done by refinancing their home loan and using equity to pay out the other debts.
Can I consolidate ATO debt?
In many cases, yes. Some lenders will consider refinancing to pay out ATO debt, particularly if you're on a payment plan and up to date with it. What's possible depends on your circumstances, including the size of the debt and your equity.
I'm self-employed. Will lenders look at my application?
Yes, and it's what we specialise in. We work with self-employed borrowers every day, including sole traders, companies and trusts, and know which lenders understand how business income works, including add-backs and alternative documentation options.
Do I need to own property?
It helps. Most consolidation options use the equity in your home or investment property. If you don't own property, we can still talk through your situation and let you know what could be available.
Will consolidating save me money?
It may lower your monthly repayments and simplify your cash flow, but spreading short-term debts over a longer loan term could mean paying more interest overall. We'll walk you through the numbers so you can see the full picture before you decide.
Will this affect my credit score?
Not at the start. Before anything goes to a lender, we run a soft credit check as part of our own assessment, and soft checks don't impact your credit score. Your score is only affected once a formal application is submitted to a lender, and we'll always talk you through that before it happens.
How long does it take?
It depends on the lender and how quickly we receive your documents, but many refinances take around 3 to 6 weeks from application to settlement.
What does the strategy session cost?
Nothing. The strategy session is complimentary and there's no obligation to go ahead. If we do proceed with your loan, we'll confirm any fees upfront, in writing, before anything is submitted.
What happens after I book?
We'll have a 30-minute chat about your debts, income and goals. If there's an option that could suit you, we'll explain next steps and what documents we'd need.
MEET THE FOUNDER & head broker
Hey, I'm Elena
I'm the broker you call when the bank has said no and you're starting to wonder if it's you. (It's usually not you. It's the way your income looks on paper.)
I started in lending at 19 as a loan support officer and taught myself the rest. I've done 10pm kitchen table meetings, chased lenders who said "computer says no", and once had my car smashed outside a client's house and still showed up the next morning.
These days I run Babo Finance, where we untangle trusts, add-backs and ATO debt for self-employed Aussies so they can get back to running their business.
$110M+ settled for 225+ clients in three years
Specialist in self-employed and complex lending
Has read more trust deeds than novels
How We Get You to One Simple Repayment
Step 1: Book your strategy session
A complimentary 30-minute chat about your debts, your income and what you want to achieve. No pressure, no obligation.
Step 2: We build your strategy
We run a soft credit check (no impact on your score), review your numbers and find the lenders that suit how your income actually works.
Step 3: Settle and simplify
Once you're happy with the plan, we handle the application through to settlement, so your debts could be rolled into one repayment.